

Free report: “5 Things $39.6M in B2B Programmatic Spend Taught Us.” Three years of managed spend and a billion tracked page loads, turned into five findings platforms won’t put in a pitch deck. Subscribe free to unlock it, plus every new issue of The B2B Stack.
Join 1,600+ B2B marketers, including readers at Dentsu, HubSpot, 6sense, Informa and DirecTV.
The week the AI stack ate the ad stack
No big M&A. No earnings shockers. No fresh Trade Desk audit drama (mercifully, since that has been the only story for a month). But pull the threads from this week together, and what you actually saw was the operating layer of programmatic advertising being rewritten in front of your face.
OpenAI flipped ChatGPT ads from CPM to CPC and dropped the floor from a quarter of a million to fifty grand. The Trade Desk shipped its first live agentic product with a named agency. PubMatic wedged custom creative into its agent OS. Magnite lost its CFO and its CPO inside a fortnight. Digiday’s quote of the week: the days of bloat are over.
This is what an industry restructure looks like when it is happening to the plumbing. Quietly. On a Tuesday.
If you sit on the demand side of B2B media, here are the four stories that actually move the road in front of you.
1. OpenAI: from experiment to ad platform, in eleven weeks
The story. On 21 April, OpenAI flipped its ChatGPT ad pilot from CPM (cost per thousand impressions) to CPC (cost per click), with bids set in a $3 to $5 range. The minimum spend dropped from the original $200K to $250K floor down to $50K. A self-serve ads manager went live. The pilot is now reported at $100M of annualised revenue after roughly six weeks of live inventory, with internal targets of $2.5B in 2026 and $100B by 2030. The CPM model collapsed because launch pricing of $60 eroded to as low as $25 inside ten weeks. International pilots in Canada, Australia and New Zealand are next. Sources: The Information (15 April), Digiday (21 April), Reuters.
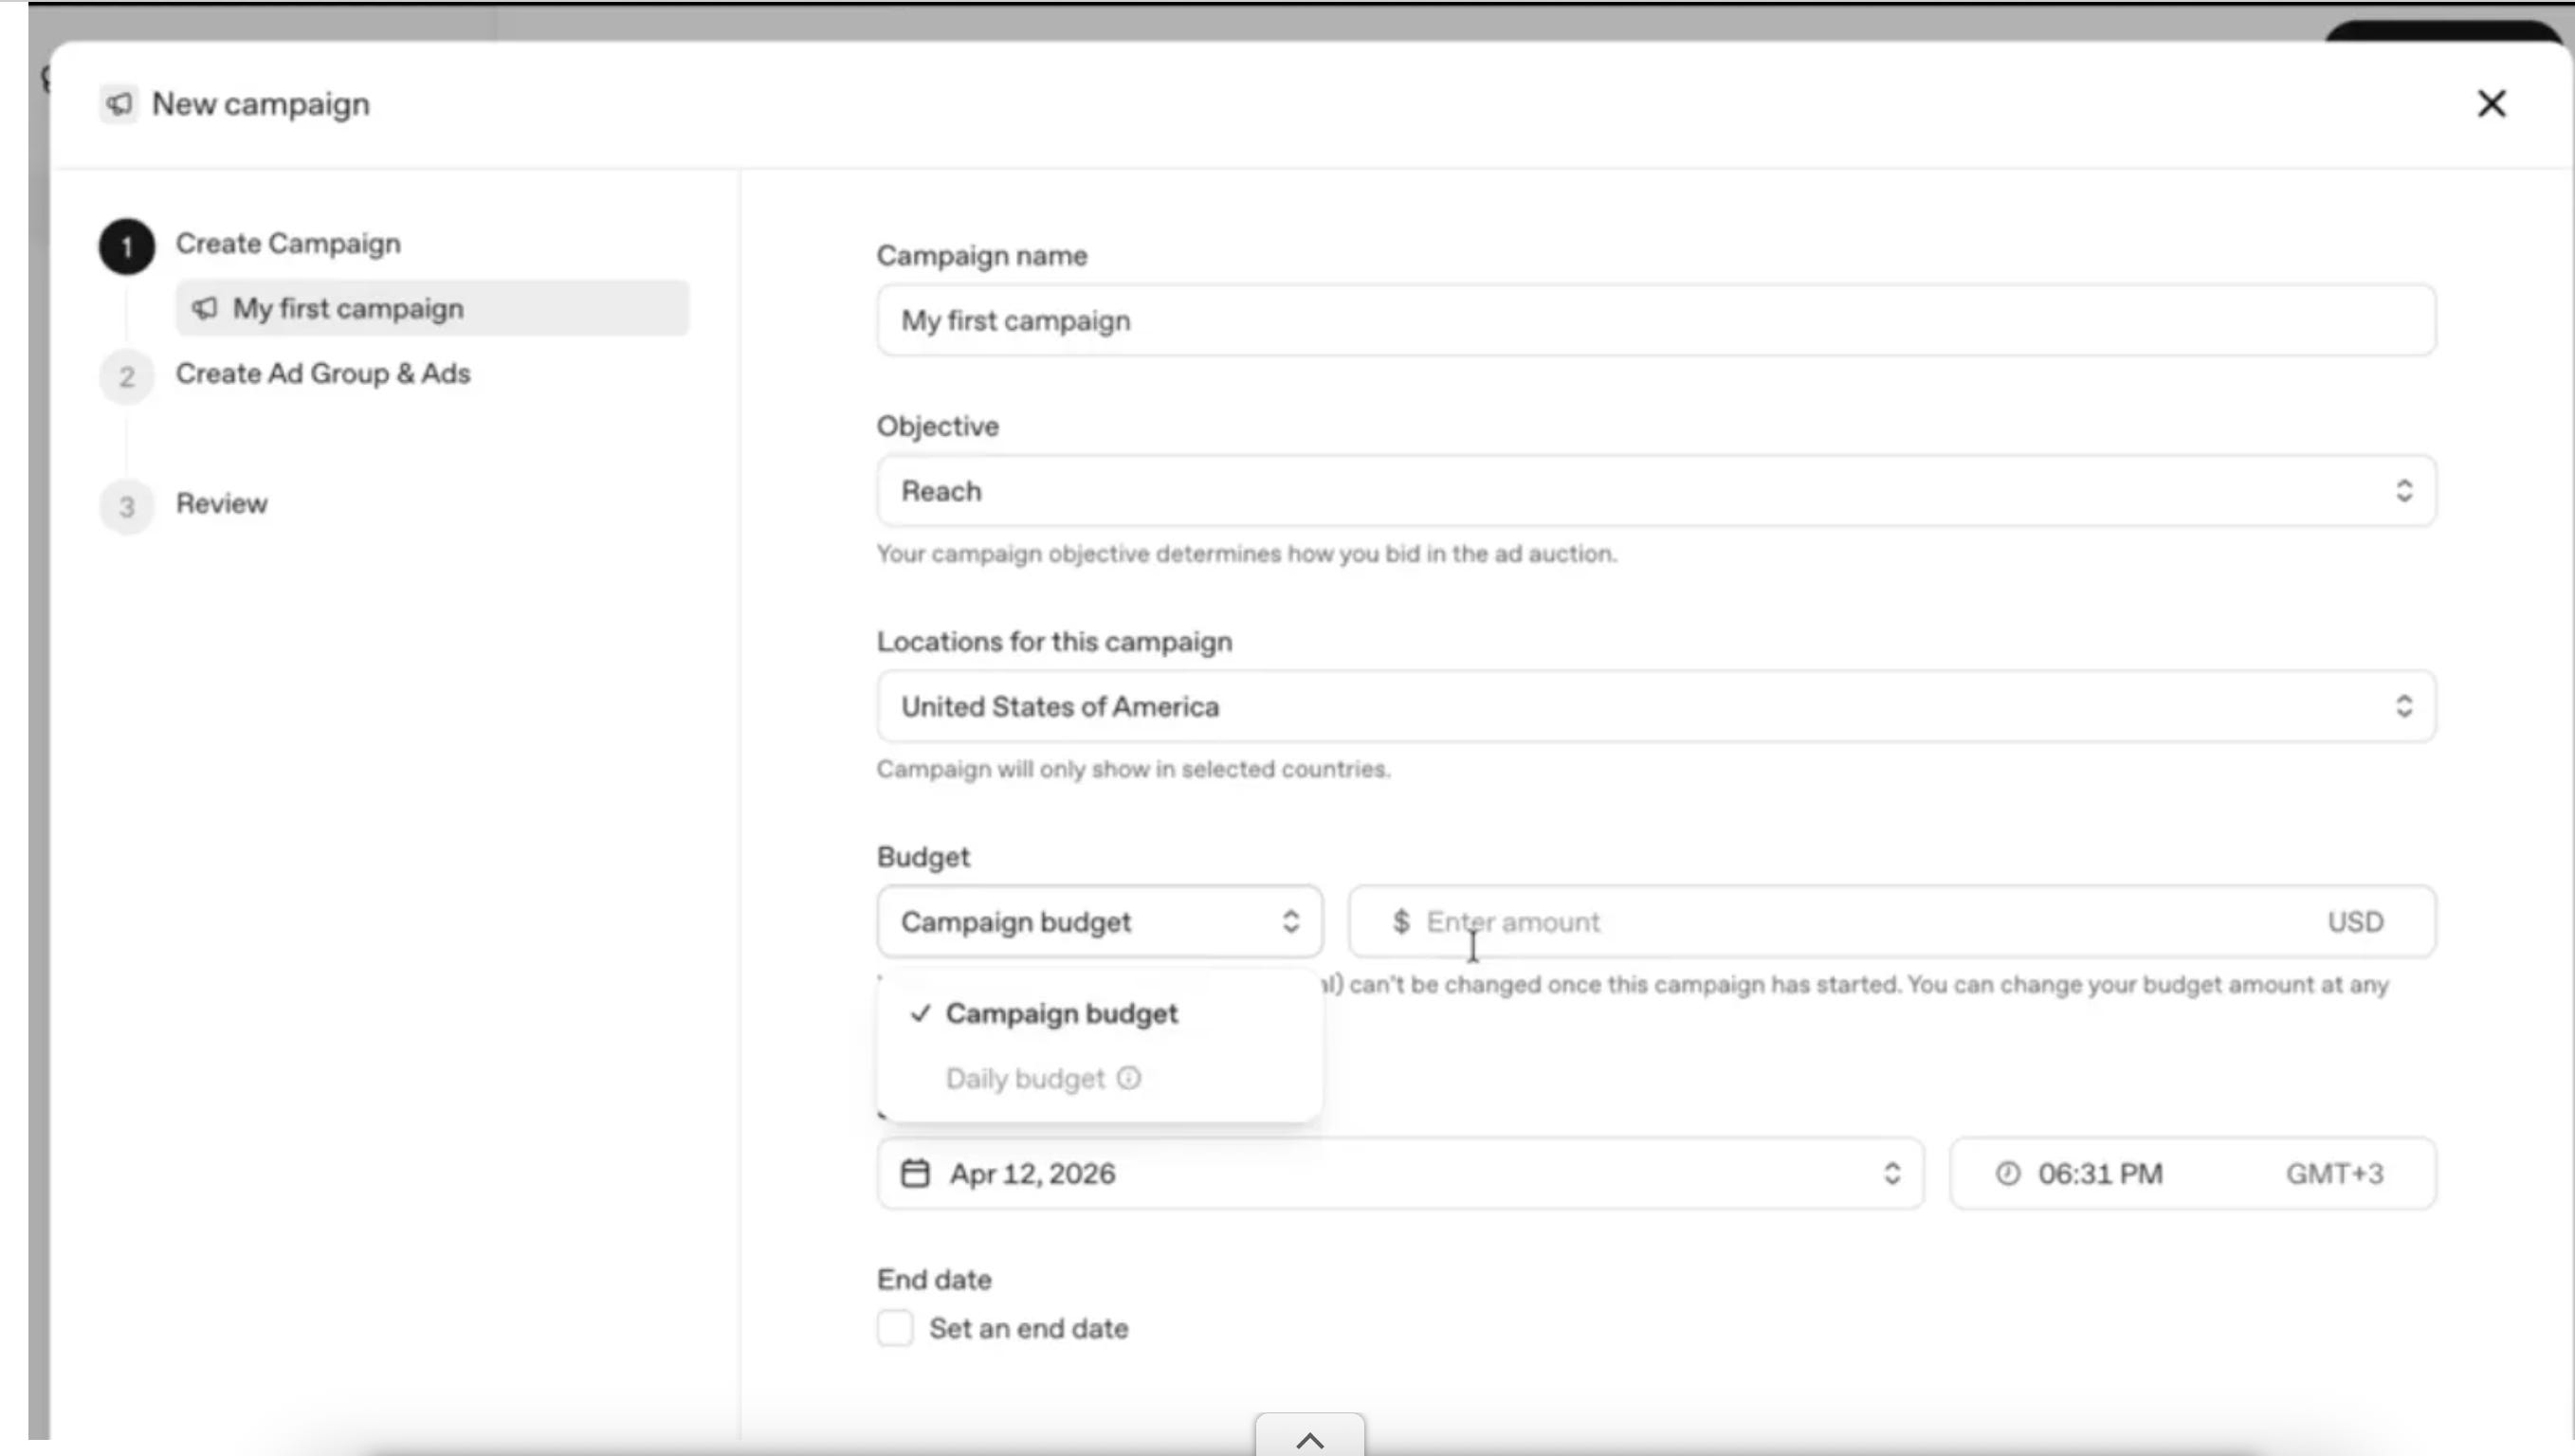
The ads manager is covered by PPC land here
My take. Forget the corporate framing of “structured pilot phase.” This is the moment ChatGPT became an actual ad channel. CPC pricing tells you everything: OpenAI could not sustain the CPM, so they are pricing on intent. $3 to $5 CPC is materially cheaper than LinkedIn (which routinely runs $8 to $15+ for B2B targeting) and broadly competitive with Google Search at the lower tail of B2B SaaS keywords.
For B2B marketers, the implication is uncomfortable. Your buyers spend a meaningful share of their vendor research time inside ChatGPT. That has been your dark funnel. As of this week, that funnel has paid placements in it that sit beside, but separate from, the AI-generated answer. Two truths follow. One: the dark funnel just got brighter on the buyer side and more contestable on the seller side. Two: if your competitors get into the pilot before you, they are training the relevance algorithm against your category. Early advertisers will accumulate algorithmic memory you cannot retroactively buy.
The catch: ChatGPT still has no proper attribution layer, no real targeting beyond contextual signal, and CTRs are reportedly weaker than search (not that we should waste energy worrying about that). Nobody has cracked B2B measurement on it yet. But “weaker than search” is not “doesn’t work” — it is the same noise you heard about LinkedIn lead gen in 2014. Get test budgets in now. Treat it as a research and brand touchpoint, not a pipeline driver, and you will not be embarrassed when your CMO asks in Q3 why you have not done anything about it.
On a personal level, I was really hoping against all hope that ChatGPT would embrace programmatic - marrying the best transparent data layering in the ad game with one of the most exciting emergent surfaces that I have seen in my career. I understand agencies have been pushing for CPC and are keen to re-stock the lost search clicks. This one may still have some miles to cover before the final shake out emerges so lets keep a watching eye
2. Agentic moves from slide deck to live deployment
The story. Three things landed in the same week. The Trade Desk launched Koa Agents in alpha with Stagwell as the named agency partner, plus an “Open Agentic Kit” integration framework (Ad Age, AdTechRadar, 21 April). PubMatic integrated its Creative Innovation Suite across AgenticOS, bringing custom creative formats into the agent workflow across CTV and mobile (PubMatic, 22 April). Yahoo, Basis and Magnite have all shipped agentic capability inside the past quarter. The IAB Tech Lab is now maintaining an Agent Registry of vetted tools.
My take. The real story is the pace of standardisation. Six months ago, “agentic” was a slide. This week it is a live feature in the major DSPs (demand-side platforms) and SSPs (supply-side platforms), with cross-industry protocols emerging. What is quietly happening is that buyer agents and seller agents are starting to negotiate inside the same frameworks, and the human in the loop is moving from execution to oversight.
For B2B this matters more than the consumer use cases the trade press leads with. B2B has long sales cycles, complex buying committees, and account-level orchestration that benefits enormously from a system that can plan, activate, optimise and report in one loop. The bit no vendor will tell you: agentic only works if the upstream signal is clean. If you feed an agent the same noisy account intent scores you have been feeding human planners, it will burn through budget faster, not smarter. The premium on raw signal quality, rather than processed platform scores, is about to get higher. This is something I have been arguing for two years. We may finally have the market context for it to land.
3. The independent ad tech squeeze is real
The story. Magnite, the largest independent SSP, announced the planned retirement of CFO David Day on 20 April, three weeks after CPO Adam Soroca departed on 8 April. Digiday’s Tuesday Ad Tech Briefing led with the headline that the days of bloat are over, and reported that independent ad tech players are facing a binary choice of bulking up or flaming out under combined LLM and walled-garden pressure (Digiday, 21 April). Hearst News also selected Magnite as preferred deal partner for high-impact formats the same week, hinting at where the surviving indies will need to specialise.
My take. Read this alongside the OpenAI story and a clear pattern emerges. The middle of the ad tech stack — independent DSPs, SSPs, DMPs (data management platforms), identity resolution layers — is being squeezed from above by LLM-mediated buying surfaces (ChatGPT, Gemini, eventually Claude) and from below by Amazon, Google and Meta consolidating end-to-end.
For B2B buyers this is significant because most of the genuinely B2B-specific tooling sits in that squeezed middle. The 6senses, Demandbases, Bomboras and StackAdapts of the world are not Magnite, but they live in the same gravitational field. Expect more M&A, more “strategic refocusing” press releases, and quiet feature deprecations through 2026. If you are renewing a multi-year contract with a B2B point solution this quarter, ask hard questions about cash runway, agentic readiness and acquisition exposure. The roadmap they show you in the QBR is worth less than the cash position on their last filed accounts.
Below are the rest of the week’s stories, and what I’d change in a B2B media plan because of them.